How Proximity to Commercial Properties Impacts Lifetime Mortgage Applications
Explore our helpful guide on how proximity to commercial properties can be considered across our lifetime mortgages.
Simon Pawson
30 Sept, 2024

Subscribe to our Newsletter on all things later finance
Join our monthly newsletter today.
By subscribing, you agree to our Privacy Policy and to receive our newsletter.
According to the mortgage criteria search system, Knowledge Bank, “proximity to commercial” is consistently in the top three most queried criteria points. Likewise, we've seen searches related to commercial criteria in the top 10 searches in our own lending criteria tool.
This is very understandable as proximity to commercial can be a complicated process since one size doesn't fit all, and for your clients to have varied borrowing options, not having a blanket answer is a good thing.
To simplify this popular topic as much as it can be simplified, I've collated a guide to commercial property proximity for financial advisers supporting later life borrowers.
Why does proximity to commercial properties pose a challenge to lifetime mortgage applications?
As lifetime mortgage providers, it's about the nature of the commercial premises, so we can understand if it could impact the property's future value or saleability. Our Underwriting team assess each case on its own individual merits and against the differing lending criteria of our product ranges.
For example, commercial properties with the potential to cause a disturbance to the resident, could be a property that is harder to sell. Potential disturbances could include:
-
Excessive and regular noise
-
Activity in unsocial hours
-
High levels of footfall or traffic
-
Emitting a smell
For these reasons, we do not favour properties in close proximity to premises such as pubs and bars, takeaways, convenience stores, etc.
Please note, this article relates to new loan applications and is accurate at the time of writing. If your client is considering additional lending, the property would be subject to a further assessment and reviewed against the applicable lending criteria at that time.
As a result, factors such as proximity to commercial premises may be considered when determining eligibility and available borrowing.
Commercial property types to be aware of
Property types where proximity needs to be addressed are generally classified as:
-
Non-residential: Schools, residential care homes, village halls, places of worship, doctors and dentists.
-
Commercial properties: Shops (small shops, convenience stores, supermarkets), hotels, offices, hairdressers, and industrial properties.
-
Licensed premises and food outlets: Pubs, bars and restaurants are typically treated separately from commercial properties in lending criteria. However, properties adjacent to or in view of these premises are generally unacceptable.
-
Home offices can be accepted provided the property remains residential, no clients visit, there’s minimal stock stored and residential council tax applies.
When reviewing proximity to commercial premises and non-residential properties, we refer to our lending criteria, the overall proposition and our Underwriting team's security assessment to determine if the property should go to valuation.
While our current criteria may support a particular property type or proximity scenario, all applications are assessed against the criteria and underwriting requirements in place at the time of application.
Even with this pre-vetting, cases are nevertheless subject to valuer's comments. We may still be unable to consider a case even if it's gone to valuation if the valuer's comments raise something detrimental regarding the proximity.
This pre-vetting process* helps us and you to streamline the lending decision for your clients. To start this process, simply send a message to our intermediary sales inbox. Email here>
* Disclaimer: In times of high demand, we may not be able to guarantee a pre-vetting process, however, our intermediary sales team can support with proximity related queries.
Commercial property scenarios we cannot typically consider
While we can often consider properties in proximity to commercial and non-residential properties, there are some circumstances where we are unable to lend, including:
-
Properties located above, or directly attached to, commercial premises. Some exceptions may apply in higher-value areas where commercial activity is unlikely to affect desirability.
-
Properties adjacent to, or overlooking, pubs, bars, restaurants or takeaways.
-
Properties that share a party wall with commercial properties.
-
Properties where the surveyor identifies concerns around future marketability, saleability or mortgageability.
Exceptions
Some non-residential properties may still be acceptable, subject to valuer comments and depending on the selected lifetime mortgage. This can include properties adjacent to, or sharing a party wall with, doctors' surgeries and dental practices.
As lifetime mortgage providers, it's about the nature of the commercial premises, so we can understand if it could impact the property's future value or saleability. Our Underwriting team assess each case on its own individual merits and against the differing lending criteria of our product ranges.
For example, commercial properties with the potential to cause a disturbance to the resident, such as creating noise, activity in unsocial hours, high levels of footfall or traffic, or emitting a smell, could be a property that is harder to sell. For these reasons, we do not favour properties in close proximity to premises such as pubs and bars, takeaways, convenience stores, etc.
Proximity to commercial properties across our lifetime mortgage products
Our lifetime mortgages do consider a variety of properties in view of, opposite, or adjacent to non-residential and commercial premises.
As the nature of a commercial premises and non-residential property impacts our decision, we do suggest you contact our knowledgeable Intermediary Sales team.
They can support you to refer a case if the situation warrants it and are a good first point of contact to check any queries related to proximity. You can find your local team here.
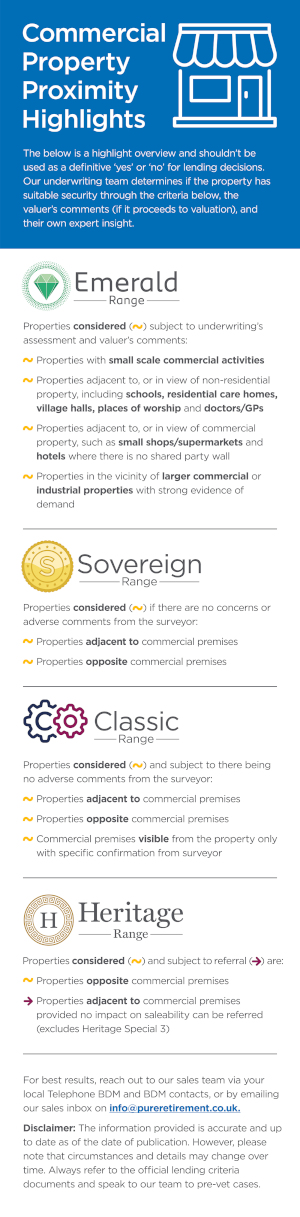
For your convenience, here is a summary from our lending criteria on how commercial premises and non-residential properties are considered across our lifetime mortgages. Please note, this information is accurate as of publishing and is subject to change.
Emerald range
Our Emerald range offers you and your clients options for properties adjacent to, or in view of, non-residential or commercial premises. We are able to consider properties under the following circumstances:
-
Properties with small scale commercial activities - small home office, no clients visiting, minimal stock kept at property, residential council tax.
-
Properties adjacent to, or in view of non-residential property, including schools, residential care homes, village halls, places of worship and doctors/GPs subject to valuer's comments.
-
Properties adjacent to, or in view of commercial property, such as small shops/supermarkets and hotels where there is no shared party wall and subject to valuer's comments.
-
Properties in the vicinity of larger commercial or industrial properties with strong evidence of demand and subject to valuer's comments.
Sovereign range
We will consider properties adjacent to or opposite commercial premises, subject to there being no adverse comments from the surveyor.
Classic range
We will consider properties adjacent to or opposite commercial premises, subject to there being no adverse comments from the surveyor.
In cases where the commercial is visible from the property, or within influencing distance, our surveyor must specifically make comment on the proximity and confirm this does not impact the value or saleability.
Heritage range
We will consider properties opposite commercial premises. We usually will not consider properties adjacent to commercial, but if it is confirmed this does not impact saleability, we may be able to consider it subject to referral. Please note, this referral option doesn't apply across the full Heritage range.
We strive to be as lenient as possible and suggest advisers contact us prior to submission for any case they are unsure about. Our goal is to help you find the best lending opportunity for your clients.
View the full lending criteria overview in our handy infographic. View infographic.
Explore the full detail in our official documents
Please view this article as a helpful guide, all official criteria can be found via our product lending criteria, which can be found in our lifetime mortgage product pages. You can also use our lending criteria tool to search for quick answers.
And to ensure your client gets a swift decision, we recommend pre-vetting any properties where proximity to commercial could impact the lending decision. Contact our intermediary sales team to start this process today.
Our resources
Explore more of our resources tailored to supporting equity release advisers like you in succeeding.
 4 minute read